

Where the World Is Buying in the UK in 2026
The story of international demand for British property in 2026 is not one of retreat or return, but rather one of reallocation. Capital is still arriving, but from different places, with different priorities, and with far greater selectivity than a few years ago. Three themes stand out: the return of the ultra-prime in London, the pull of the countryside, and the changing shape of the international household.
London: The Ultra-Prime Rebounds
The capital offers the clearest signal. Industry data shows 34 completed sales above £15 million in the first half of the year, up 26 per cent on the same period in 2025 and worth £1.24 billion. Separate market data puts sales of £10 million and above in the second quarter 24 per cent higher year on year.
Who is buying matters more. American and Gulf buyers now account for 55 per cent of ultra-prime transactions, and the American share alone has risen from 20 to 30 per cent. Many work in technology, artificial intelligence and private equity. They tend to be younger than their predecessors, decisive, and comfortable paying for rarity.
Beneath this sits a quiet exchange of owners. Industry data indicates that around 70 per cent of vendors of £15 million-plus London homes in 2025 were non-domiciled residents relocating abroad, most often to Dubai. Gulf buyers have taken up many of those homes, a reciprocal flow that has kept the top of the market liquid while sentiment elsewhere softened. The buyers replacing them are younger, with wealth built more recently in technology and finance, and they tend to treat London as one anchor among several rather than a permanent base.
A Market That Rewards The Patient
Pricing has helped. Prime central London values fell 4.8 per cent in 2025, and a February index showed many central addresses back at levels last seen in 2013. For well-advised cash buyers, particularly in the £2 million to £10 million bracket, negotiating room has returned and vendors have every reason to price realistically. Buyers are also weighing annual running costs, from service charges to new property taxes, as carefully as the purchase price.
Beyond The Capital: The Cotswolds and the Home Counties
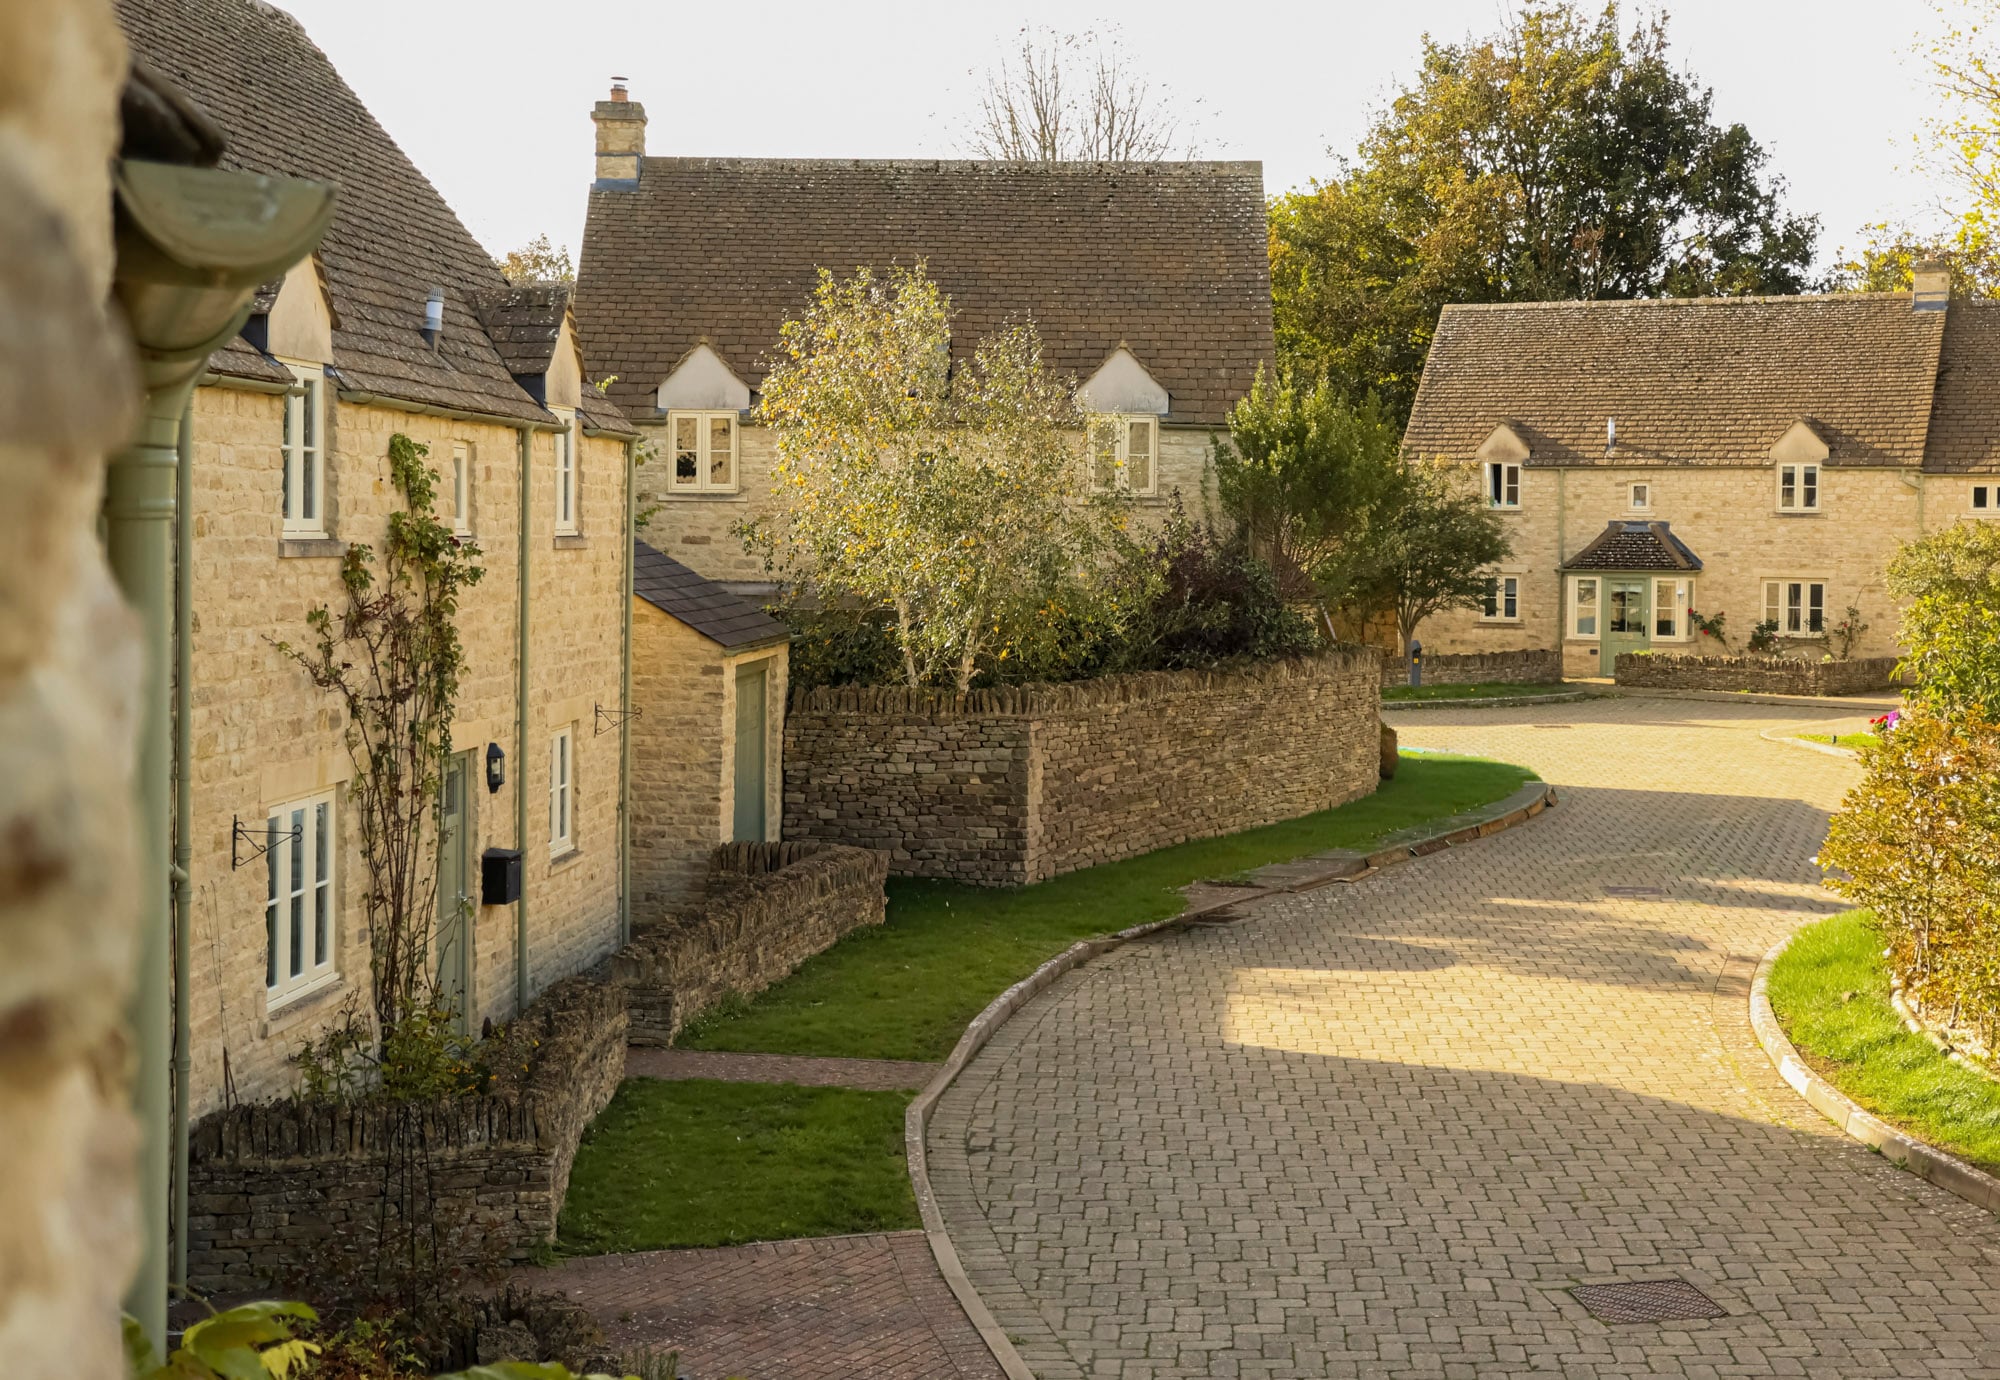
The more interesting movement is outward. Industry data points to prime country prices stabilising from late 2025, with American demand singled out as particularly strong. In the Cotswolds, international buyers accounted for just over a fifth of sales above £1.5 million last year, alongside relocators and second-home buyers from the capital. Domestic demand remains strong too, with needs-based upsizers accounting for almost half of buyers in one recent regional study, which means international buyers are competing rather than simply arriving at an open field.
Their brief is consistent: restored farmhouses, manor houses and village homes that pair architectural integrity with contemporary comfort, ideally ready to live in. Many already own in London, Ibiza or further afield, and have little appetite for a renovation project. Across the South East and well-connected rural areas, access, schooling and community decide the shortlist. Wentworth, with its celebrated golf courses, continues to hold ultra-high-net-worth interest, while supply at the very top remains limited.
Knowledge Corridors
A quieter, investment-led story is unfolding in Oxford and Cambridge, where planning constraints limit delivery and a high-income tenant base of researchers, executives and international talent sustains demand for prime rentals. The case here rests on yield and long-term scarcity rather than lifestyle.
The Multi-Home Family
Perhaps the most telling shift is behavioural. Research suggests families are splitting the way they live, perhaps to an unprecedented degree, moving between properties annually or seasonally and following social calendars. A London townhouse, a country house within reach of the season’s events and perhaps a coastal retreat can now form a single portfolio. The brief changes accordingly: homes that are easy to leave and easy to return to, in places with a genuine community around them.
The Year Ahead
For sellers, the lesson is that international buyers have not gone; they have become more discerning. Demand concentrates on the rare, the well-presented and the correctly priced, and buyers who find it will often move quickly. Overpriced or tired stock, by contrast, is meeting resistance, which is why realism at launch matters more than at any point in recent years.
For buyers, the opportunity lies in the same discipline. A repriced market, motivated vendors and real choice between London and the shires reward those who know precisely what they want. With confidence returning, and the ultra-prime figures suggesting it has already arrived at the top, that window is unlikely to stay open indefinitely.
In 2026, the UK is not attracting global buyers so much as a more selective, more mobile and more informed kind of global buyer, and the markets that meet them with honesty and quality will thrive.
Read More