

Can Americans Buy Property in the UK?
For many Americans, owning a home in the UK represents more than a property purchase. It can mean having a London base, a countryside retreat, or a home where you can experience one of the world’s most culturally rich and internationally connected countries. The UK offers an exceptional variety of homes, from contemporary apartments in Battersea and Georgian townhouses in Mayfair to grand country estates beyond the capital.
But can an American citizen actually buy a home in Britain? The answer is yes. American citizens can purchase property in the UK, whether intended as a primary residence, second home, or investment, although purchasing a property does not itself confer the right to live in the country.
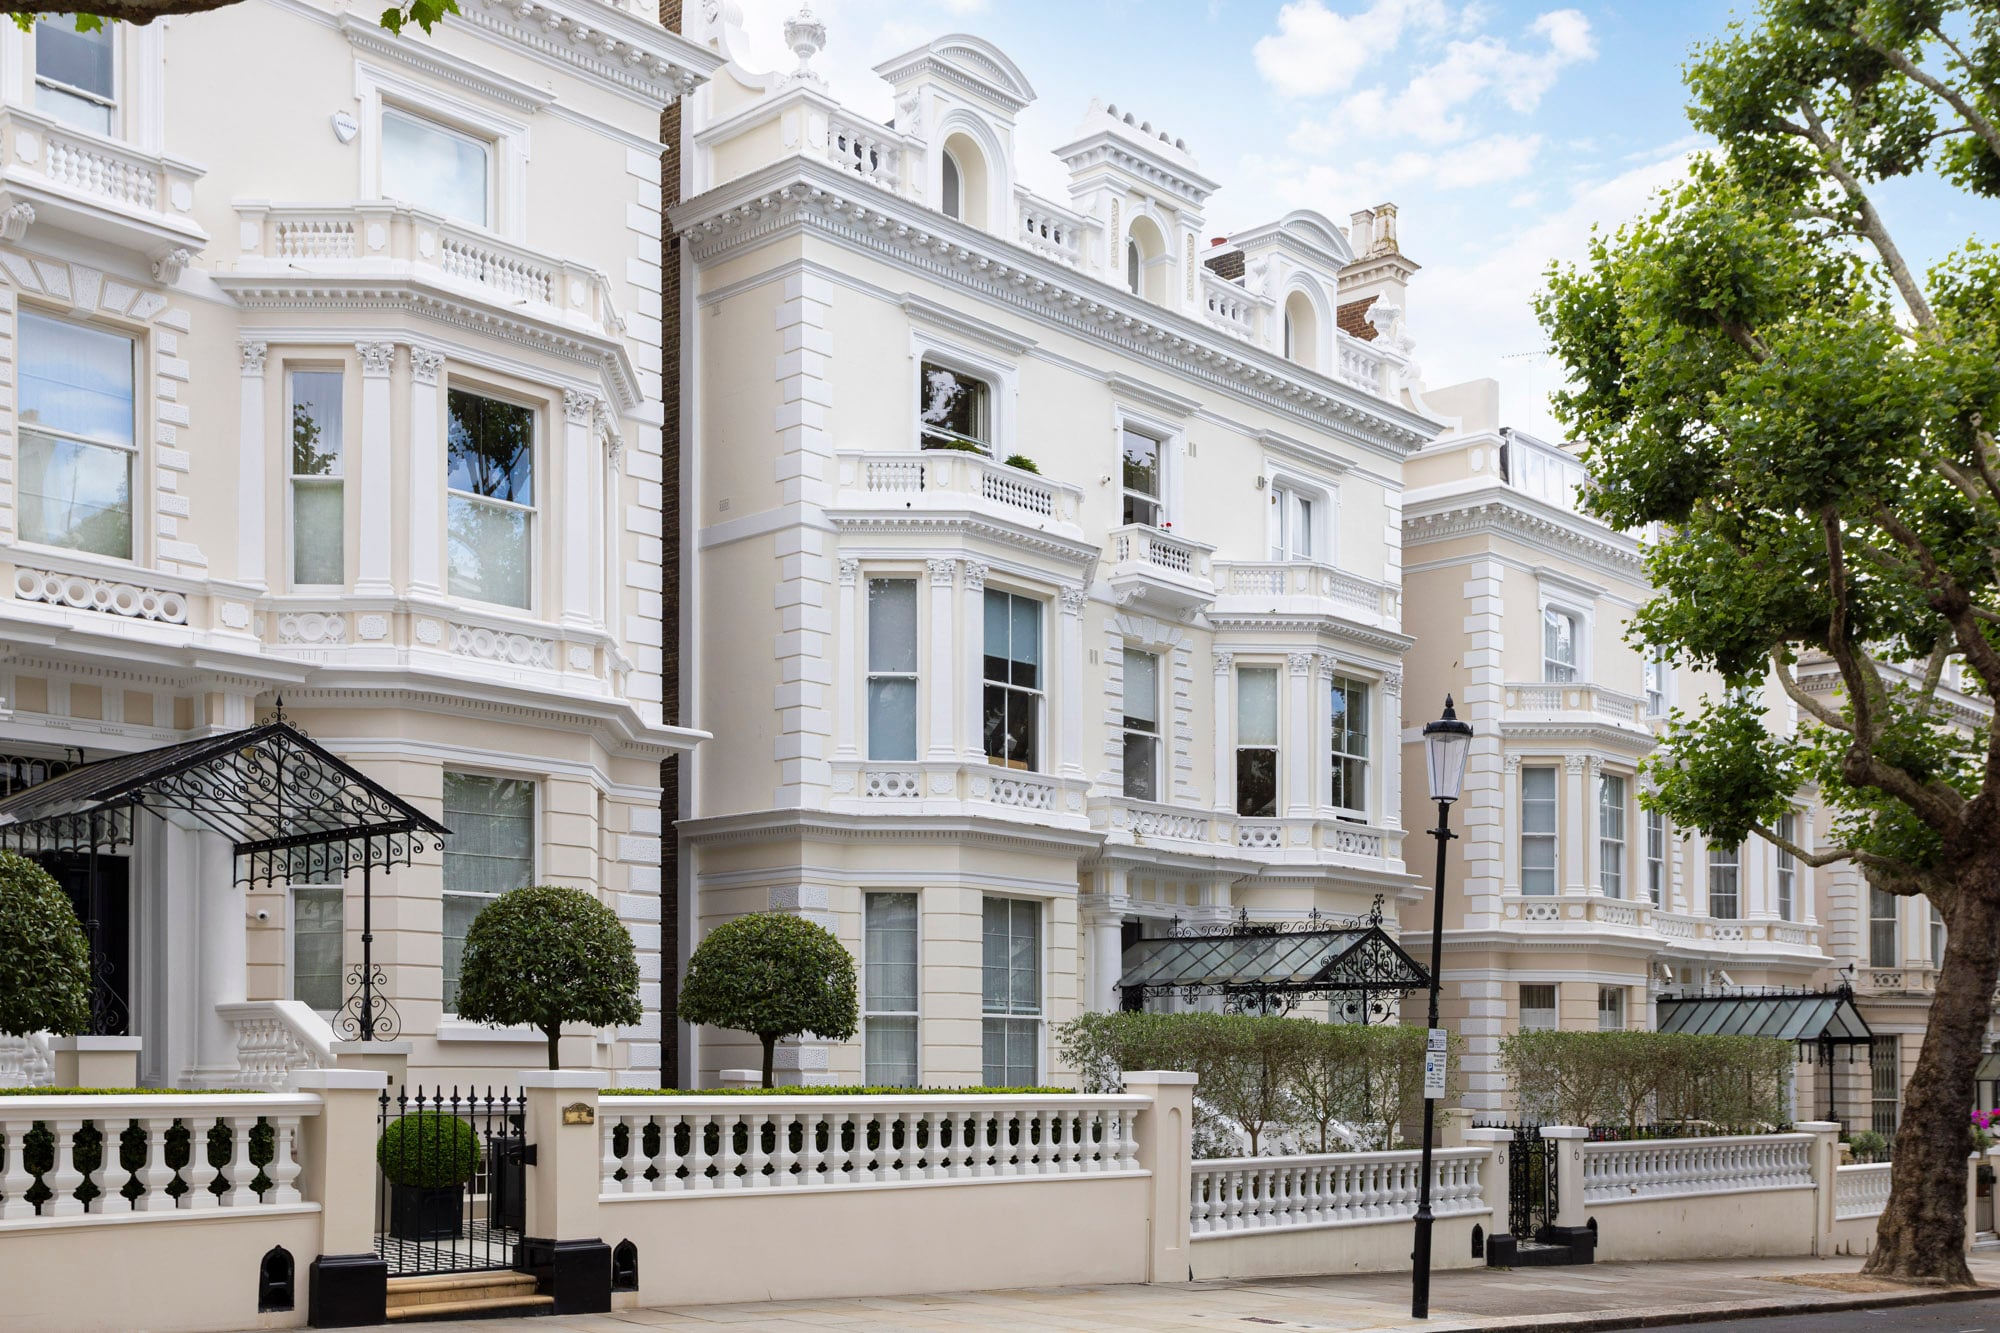
A Market Open to International Buyers
The UK is generally open to overseas buyers, and American citizens do not need to hold British citizenship to purchase a property. This makes it possible to own a home in Britain as a second residence, an investment, or a place to stay when visiting. It is important to distinguish property ownership from residency, however, as buying a home does not grant the right to live in the UK or provide a visa. Anyone planning to spend extended periods in the country should therefore consider the applicable immigration requirements separately.
For many international buyers, the appeal is therefore not necessarily relocation. A property can instead provide a private base in London for business and leisure, a home for family visits or a place to return to throughout the year for a change of scenery.
London and the Appeal of a Global City
For American purchasers, London can feel familiar in some respects, yet distinctly different in others. English is the predominant language spoken in the UK; the city is deeply connected to the United States through business and culture, and direct flights link London with major American cities. Yet its architecture, neighbourhoods and history offer a very different sense of place. Prime central areas such as Mayfair, Belgravia, Chelsea, Knightsbridge and Kensington combine historic architecture with restaurants, galleries, boutiques, green spaces and some of the capital’s most established institutions.
Beyond London, American buyers may also be drawn to the character of the English countryside, from Surrey and Oxfordshire to the Cotswolds and beyond. Here, the appeal lies in a different rhythm of living: historic homes, expansive gardens, village communities and proximity to the capital.
What Taxes Do American Buyers Pay?
For American buyers, understanding the tax implications of purchasing property in the UK is an important part of the process. Stamp Duty Land Tax (SDLT) is one of the main costs to consider, with the amount payable determined by the property’s value and the buyer’s circumstances. Non-UK residents may face an additional surcharge, while higher rates can also apply to those who already own residential property elsewhere. On more expensive homes, these costs can add considerably to the overall purchase price.
The tax position can become more involved where a property is bought through a company. Depending on the circumstances, this may result in higher SDLT rates and could bring the Annual Tax on Enveloped Dwellings (ATED) into consideration. Capital Gains Tax may be payable when the property is sold, and UK Inheritance Tax can apply to UK-situated property irrespective of the owner’s nationality or place of residence.
As American and UK tax rules may overlap, and the treatment can vary according to personal circumstances and ownership structure, professional advice from advisers familiar with cross-border taxation is strongly recommended before committing to a purchase.
Buying with Dollars, Mortgages and Due Diligence
For an American buyer purchasing property in pounds sterling, currency becomes another important consideration. The exchange rate between the US dollar and pound can influence the overall cost of a purchase, particularly at higher price points. Buyers transferring substantial amounts of money internationally should consider how currency movements, transfer arrangements and related banking costs may affect the transaction.
However, financing is also possible, although the mortgage options available to an overseas buyer can differ from those available to a UK resident. Some international purchasers choose to buy with cash, while others explore specialist mortgages through lenders experienced in cross-border transactions. Regardless of how a property is financed, due diligence remains an essential part of the process. Buyers will generally need to provide identification and evidence relating to their source of funds, while solicitors and other professionals will undertake the necessary legal and regulatory checks.
Choosing the Right Property
For an overseas buyer, the right property is rarely defined by its address alone. A London townhouse might offer proximity to the city’s cultural life and a sense of permanence. A contemporary apartment may provide convenience, security and access to a range of amenities, while a country house can offer privacy, space and a closer connection to the surrounding landscape.
The intended use of the property should shape the search. Someone seeking a family home or a long-term base may place greater emphasis on space, schools and neighbourhood character, compared with a buyer looking for a smaller, more manageable apartment. For those considering a property as an investment, rental demand, maintenance costs, taxation and the property’s long-term positioning within its local market should also be assessed carefully.
The most compelling properties often bring several qualities together: architecture with character, a strong sense of place, thoughtful design and a location that continues to offer relevance beyond the purchase.
Read More